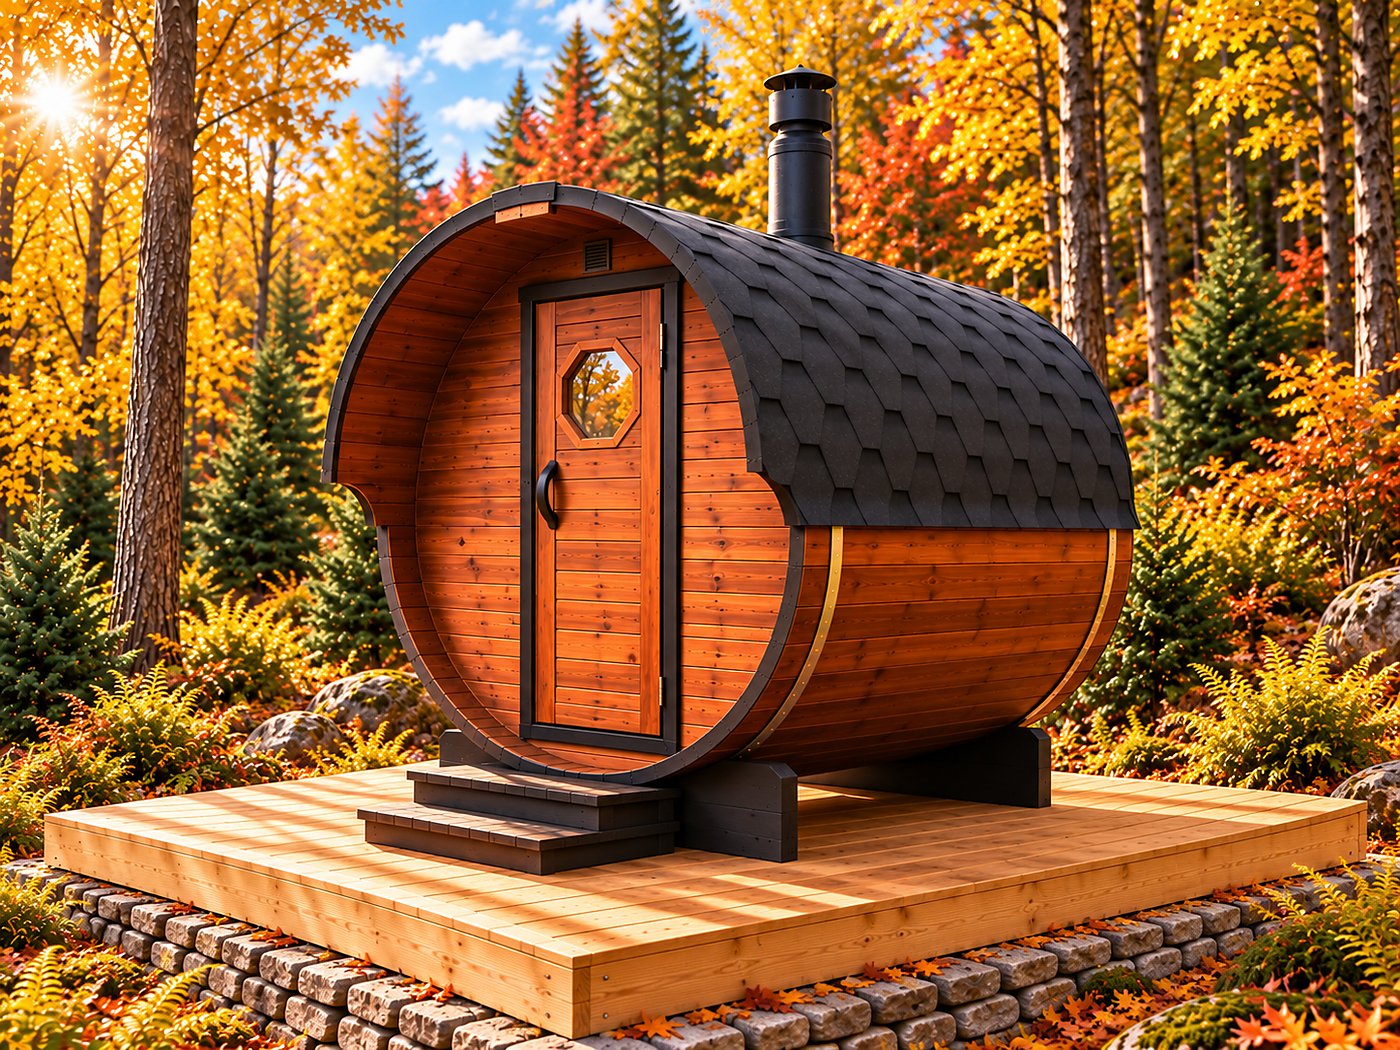
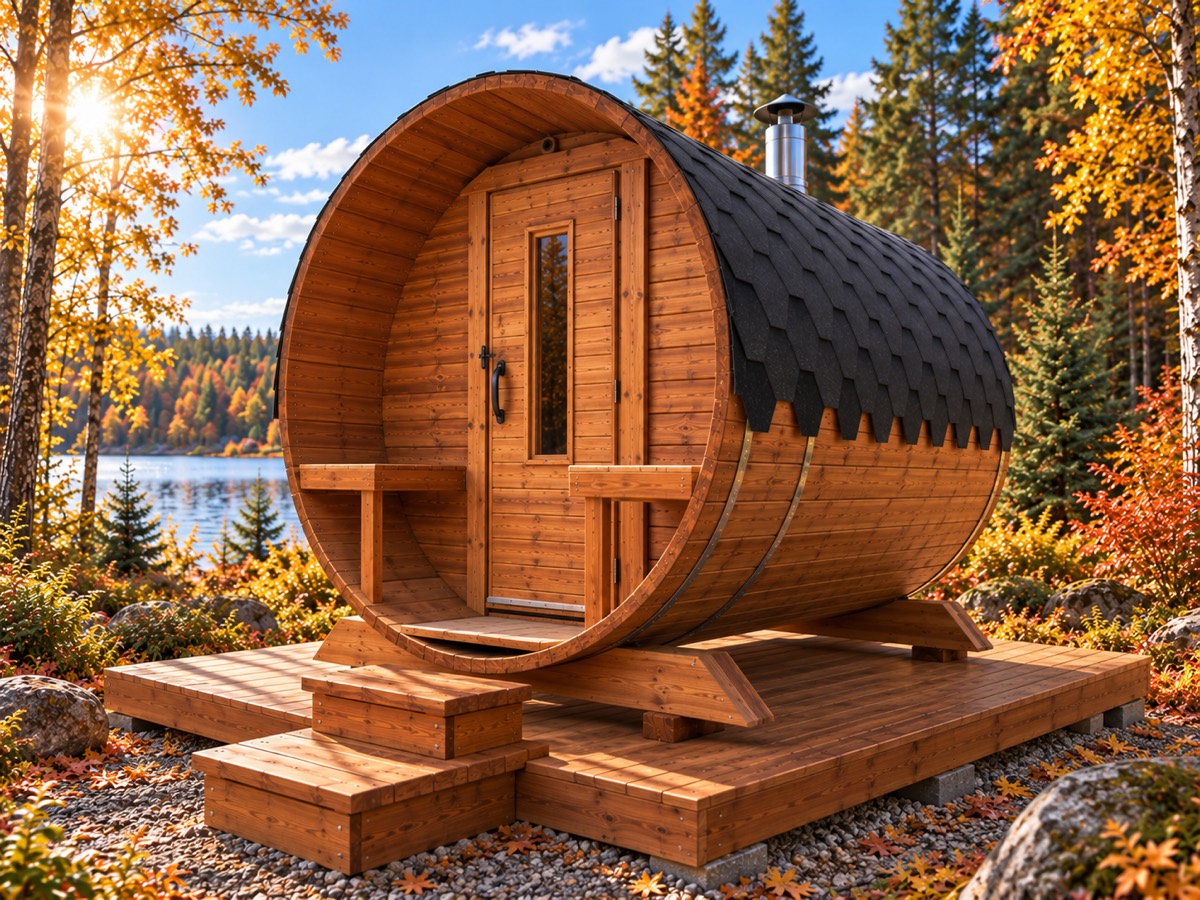
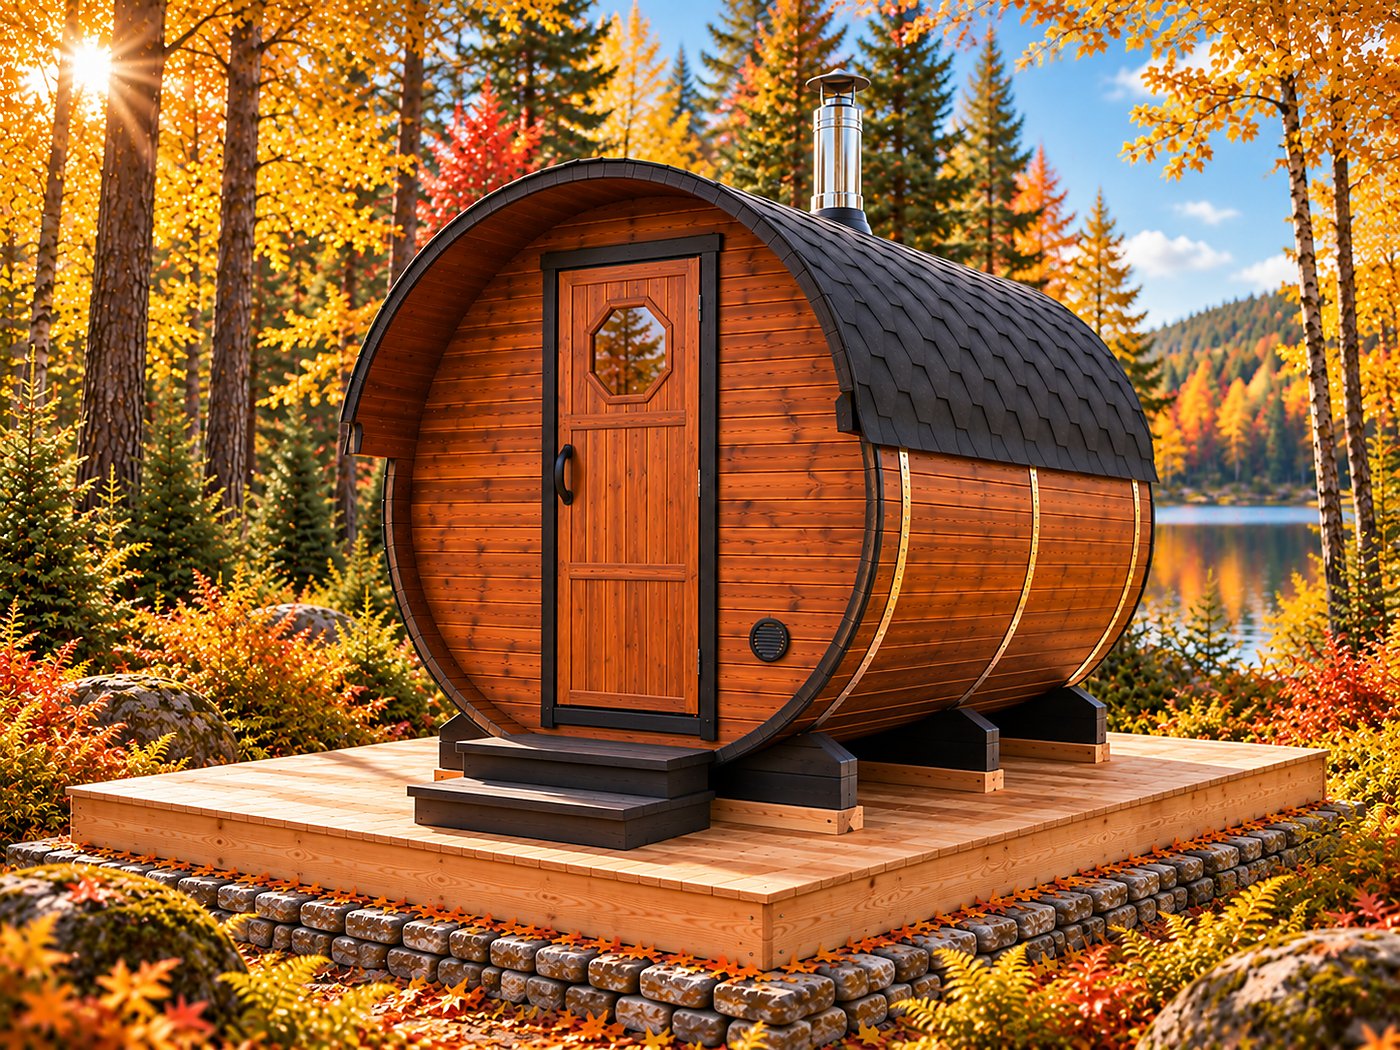
Sauna on an allotment: what to know before you buy
Garden sauna on an allotment plot: tenancy rules, permission from the site, wood-fired or electric stove, power supply. Check first, then order.
Read →These are questions that usually only come up after the purchase, but they should be settled beforehand. A lot depends on one decision: whether the sauna gets a foundation. This is general guidance; your insurer and, where relevant, your accountant decide your specific case.
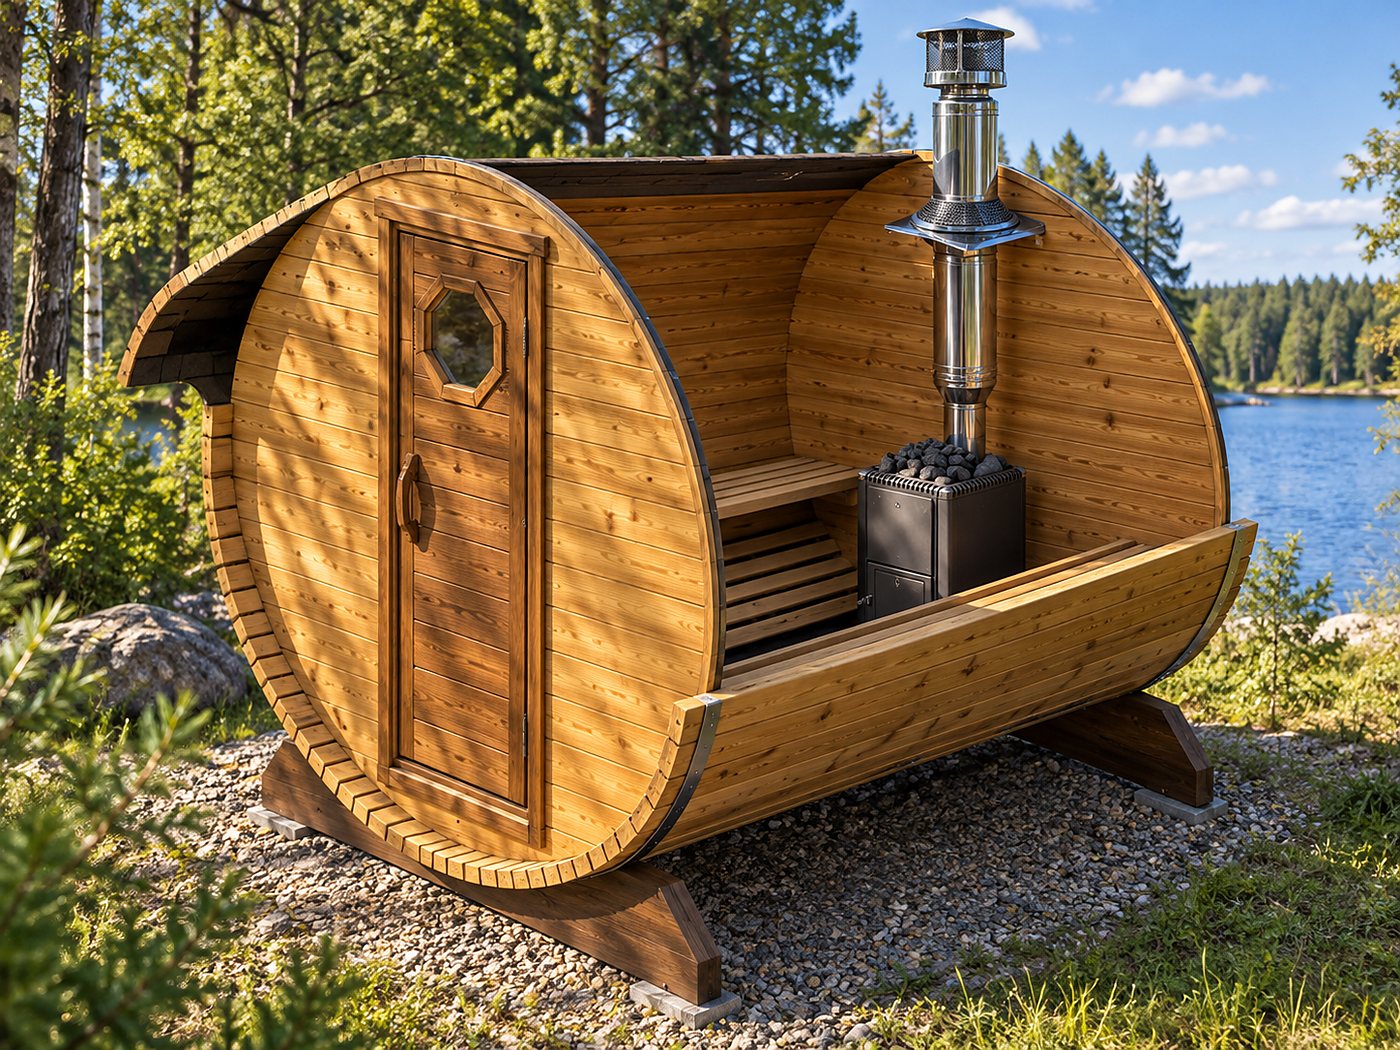
Buildings and home insurance policies often include outbuildings in the garden, but not always and not automatically.
A sauna with a wood stove is a structure with a fire in it, and insurers treat it separately for that reason. Sometimes it is excluded from the basic cover.
The simplest thing is to ask directly: is a garden sauna with a wood stove covered, up to what value, and does the premium change? One phone call.
That the sauna exists, especially if its value is above the limit for outbuildings or garden items in your policy.
That it has a wood stove. If you do not mention it, that can be a reason to refuse a claim after a fire, and fire is exactly the case where sauna insurance really counts.
The replacement value rather than the purchase price, if your policy distinguishes between them.
If a spark from the chimney causes damage next door, you are liable. A spark guard on the chimney costs little and in wooded areas is part of the essential equipment, not an extra.
Check whether your personal liability cover includes something like this. It usually does, but the scope can differ.
Whether an outbuilding matters for local property taxes or rates depends on the individual case. A sauna without a foundation that can be moved as a whole is the simpler case.
With a poured concrete foundation and fixed connections, ask your local authority or accountant if in doubt, before rather than at some later reassessment of the property.
If the sauna is to run for guests, in a holiday flat, a holiday let or as part of a mobile sauna hire business, private insurance is usually not enough.
You generally need business insurance with third-party liability cover. Tell the insurer openly what the sauna is used for.
First decide whether there will be a foundation. That one decision affects all the other topics at once.
Then one phone call to your insurer.
With a foundation, one question to your accountant or local authority.
Together that is a quarter of an hour, and the subject is settled for years.
Name and phone number — we will message you on WhatsApp, help you pick the size and price it with delivery to your address.
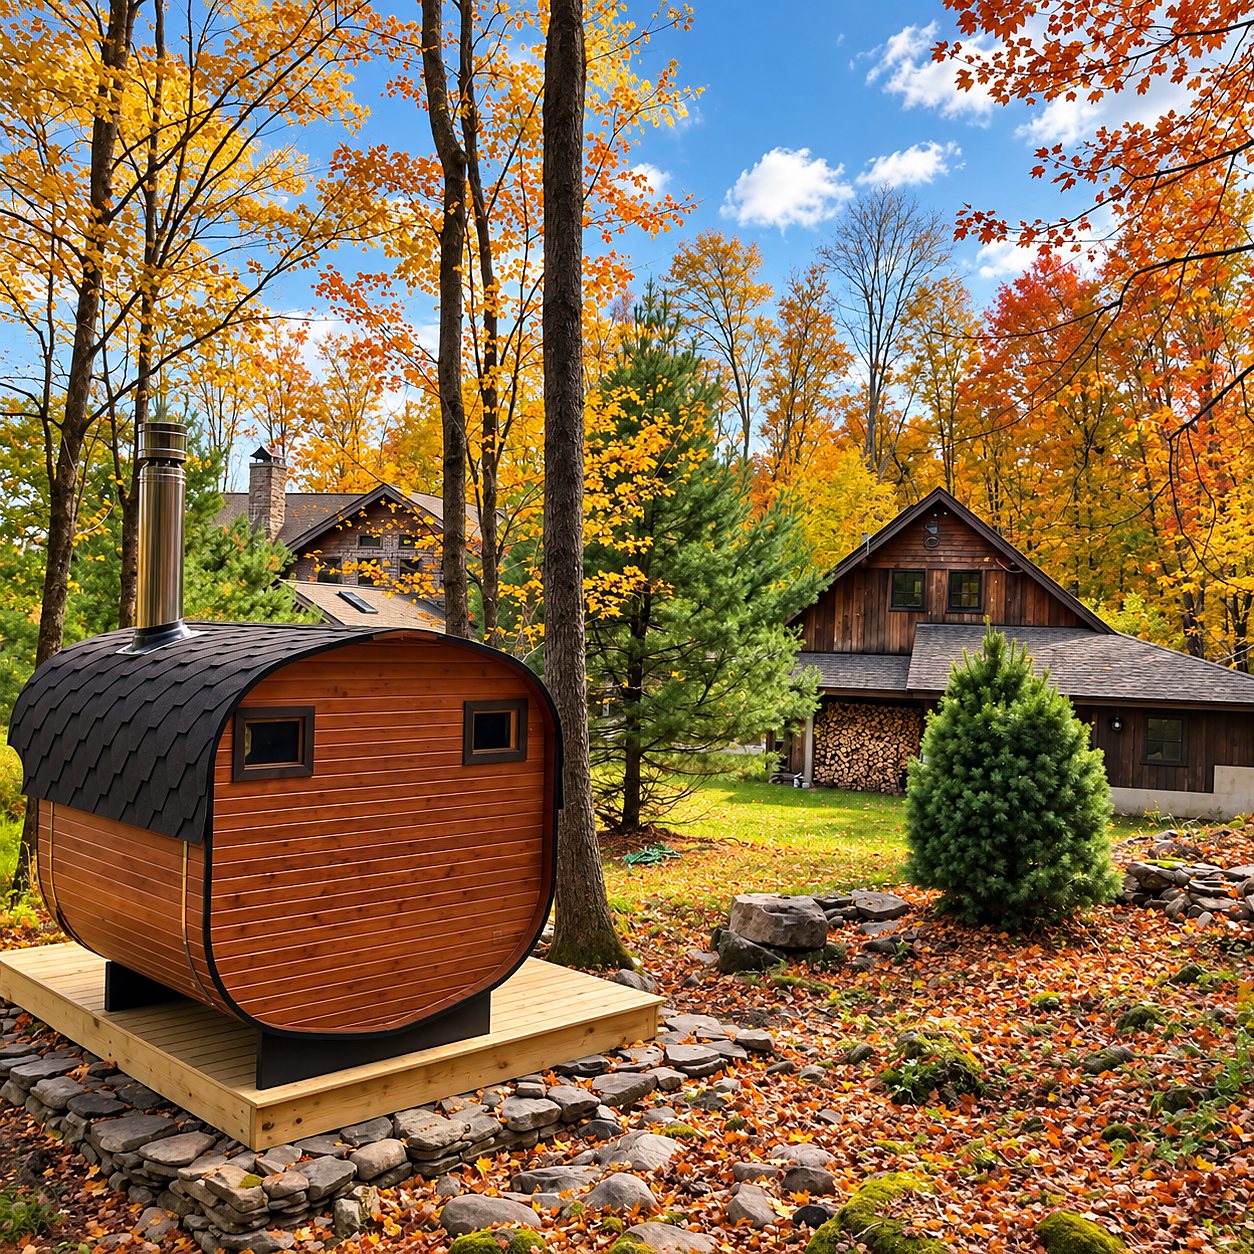
Garden sauna on an allotment plot: tenancy rules, permission from the site, wood-fired or electric stove, power supply. Check first, then order.
Read →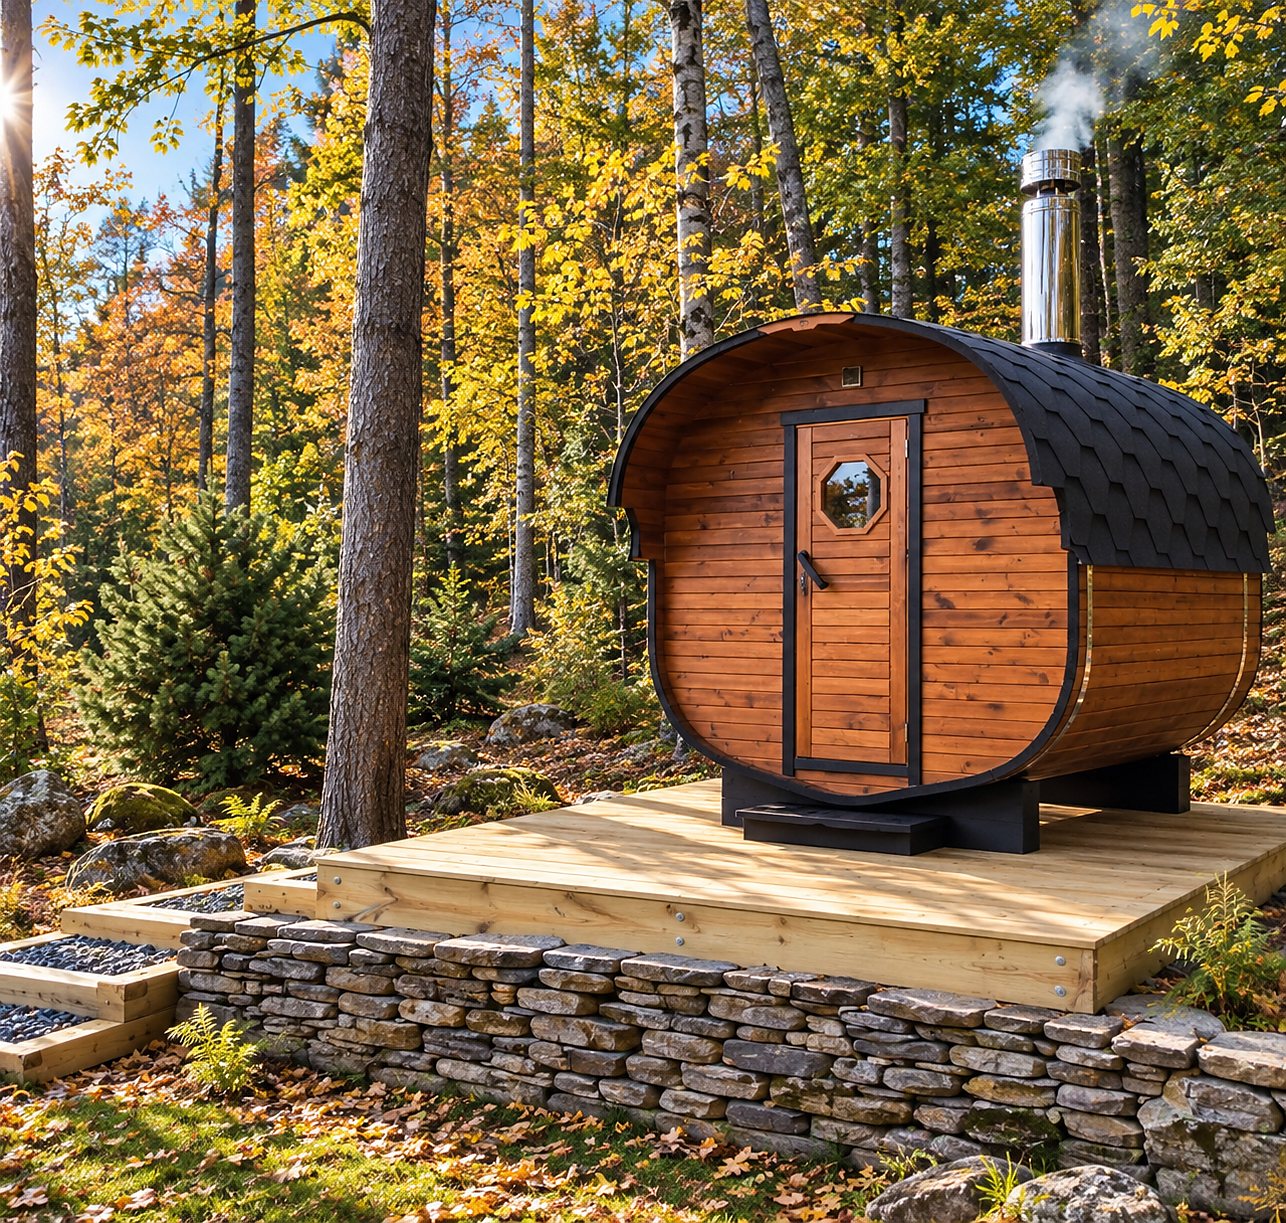
Ten mistakes that cost the most, from comparing prices on different tax bases to buying too big. All of them can be spotted before you order.
Read →Buying a used garden sauna: how much you really save, what is cheap to repair and which defects should rule out the purchase for good, whatever the price.
Read →Name and phone number — we will message you on WhatsApp, help you pick the size and price it with delivery to your address.
Cookies
Besides the essential ones, we use cookies for visit statistics and measuring ad performance. We turn them on only with your consent. Privacy.